
Investing works best when it begins with a purpose. A home down payment, an emergency fund, education costs, and retirement savings may all be important, but they should not necessarily be invested the same way. Questrade, a Canadian investment firm offering self-directed investing and managed portfolio services, explains these core decisions in its guide on how to build an investment portfolio, including financial goals, asset allocation, diversification, account types, and ongoing portfolio reviews.
A strong plan does not require constant trading or a complicated collection of investments. It requires a realistic connection between the money you earn today and the life you want that money to support later.
Why Goals Should Come Before Investments
Choosing investments before defining their purpose can cause problems. Money needed in two years for tuition or a vehicle serves a different goal than retirement savings decades away. Success isn’t just earning the highest return; it’s having enough when needed while taking a tolerable level of risk.
Goal-based investing gives every dollar a purpose, helping you avoid emotional decisions during market declines. Rather than reacting to headlines, check whether your timeline, savings rate, and investment mix still support your goal.
How to Map Money to Life Goals
Start with a short list of goals, then give each one a practical structure:
- Name the goal, such as an emergency fund, home purchase, career break, or retirement.
- Estimate the amount you may need.
- Choose a target date or date range.
- Decide how quickly the money must be accessible.
- Set a monthly contribution that fits your budget.
- Revisit the plan after a major change in income, family, debt, or housing.
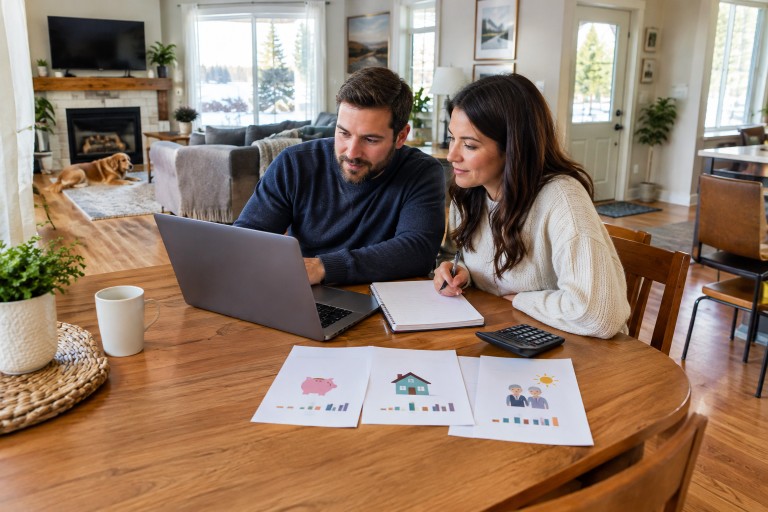
A simple goal map might look like this: an emergency fund for immediate access, a down payment for use in about five years, and retirement savings for use much later. Separating these goals helps prevent short-term needs from being exposed to long-term investment risk.
Match Each Goal to a Time Horizon
Time horizon is the period before you expect to need the money. Short-term savings often need stability and access. Medium-term money may need a balance between growth and protection. Long-term money may have more time to recover from normal market swings, although a long timeline does not automatically make any risky investment suitable.
- Short term: emergencies, travel, planned purchases, or near-term tuition.
- Medium term: a home purchase, career change, business goal, or future education costs.
- Long term: retirement, legacy planning, or goals more than a decade away.
Set a Risk Level That Fits the Goal
Risk tolerance is your comfort with investment fluctuations; risk capacity is how much loss your finances can absorb. Though related, they differ: you may tolerate market declines but need stability if you’ll soon need the money.
Consider income and job stability, debt, emergency savings, and household responsibilities. Higher returns usually mean greater uncertainty. Questionnaires can help, but shouldn’t replace careful consideration of your circumstances.
Build a Balanced Investment Mix
Asset allocation is a portfolio’s investment mix: stocks offer long-term growth potential, bonds and other fixed-income assets provide income or relative stability, and cash or savings products support access and capital preservation. Funds and ETFs bundle securities, while individual holdings need more monitoring.
Review management expense ratios, trading, advisory and account fees, plus foreign-exchange costs where applicable. Multiple funds may appear diversified yet hold many of the same companies, sectors, or markets.
Choose the Right Canadian Account Type
An account is the container, while investments are what you hold inside it. The account can affect tax treatment, contribution limits, and withdrawal rules.
TFSA
A TFSA can support both short- and long-term goals, depending on the investments held inside it. Before contributing or withdrawing, check your available room and the current rules for a Tax-Free Savings Account.
RRSP, FHSA, and Non-Registered Accounts
An RRSP is commonly used for retirement planning, but withdrawals can have tax consequences. An FHSA may be relevant for eligible first-time home buyers, while a non-registered account can provide flexibility after registered account room is used. Eligibility and contribution rules for a First Home Savings Account should be confirmed before acting.
Use Diversification With Care
Diversification means spreading exposure across companies, sectors, asset classes, and regions. It can reduce the impact of one weak holding, but it cannot prevent losses during a broad market decline. Review your portfolio for heavy exposure to one employer, industry, country, or group of overlapping funds. International holdings can also introduce currency risk.
Create a Simple Review System
A review once or twice a year is often more useful than daily checking. Confirm that your goals and dates still make sense, measure progress toward contribution targets, review costs and overlap, and compare your current mix with your intended mix. Marriage, divorce, a new child, job loss, inheritance, home purchase, or approaching retirement can all justify a review.
A Practical Canadian Example
Consider a fictional 32-year-old with three priorities: a $15,000 emergency fund, a $60,000 down payment expected in five years, and retirement savings for more than 25 years in the future. The emergency fund may call for readily accessible savings. The down payment may require a cautious approach because the purchase date is relatively close. Retirement savings may have a longer horizon, but the investor still needs a mix they can hold through market declines.
This example is educational, not personal financial advice. The right approach depends on the person’s income, debts, household needs, tax position, and ability to handle losses.
Frequently Asked Questions
How much should a beginner invest?
Start with an amount you can repeat consistently after covering essential expenses, debt obligations, and emergency needs. A sustainable contribution is usually more valuable than an ambitious amount that stops after a few months.
Should short-term savings be invested?
Money needed soon may need greater stability and easier access than money intended for long-term retirement goals.
Can a portfolio change as life changes?
Yes. Changes in income, family responsibilities, timelines, and risk capacity may justify adjusting your savings targets, account choices, or investment mix.
Conclusion
The most useful investment plan starts with the life it is meant to support. Define each goal, set a realistic timeline, choose an approach that matches your need for access and stability, and review the plan as circumstances change. The best portfolio is not always the most complex one. It is the one you understand, can maintain, and can keep connected to your real financial priorities.